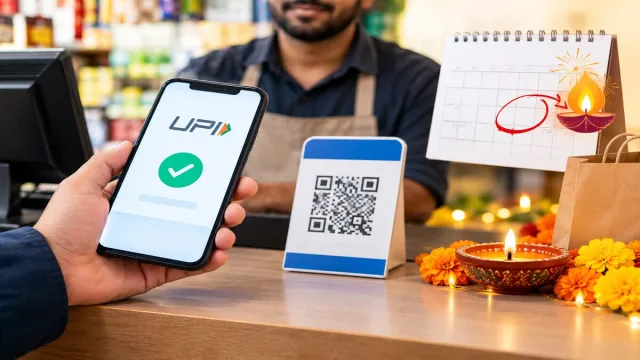
India’s proposed merchant discount rate framework for selected UPI transactions has been postponed until after Diwali, according to an Economic Times report published on October 13. The framework had been scheduled to take effect on October 15 and proposed a 0.4% merchant fee on eligible bank-account-funded payments above ₹2,000, capped at ₹300 per transaction. The postponement gives businesses and payment companies additional time to prepare, while the revised implementation date remains unannounced.
India’s digital payments ecosystem is preparing for a potential change in how certain merchant transactions are priced.
The National Payments Corporation of India had announced a merchant discount rate framework in September, with an October 15 implementation date. The rollout has now been deferred until after Diwali, according to The Economic Times. <Cite refs={[“turn794878search1”]}/>
The delay is significant because UPI has become one of India’s most widely used payment methods, serving consumers, small merchants, large retailers and online businesses.
Any change to merchant transaction costs can affect the way businesses assess payment options and manage operating expenses.
What the proposed framework would do
The reported framework proposes a 0.4% fee on eligible bank-account-funded merchant UPI payments above ₹2,000, subject to a maximum fee of ₹300 per transaction. <Cite refs={[“turn794878search1”]}/>
It is important to distinguish this proposal from the claim that every UPI payment will become chargeable.
The reported framework concerns a defined category of merchant transactions. It should not be interpreted as a universal fee on all person-to-person transfers or every small UPI payment.
The exact treatment of individual transactions depends on the final rules and applicable payment arrangements.
Why the rollout matters to merchants
UPI’s popularity has been partly associated with its ease of use and low-friction payment experience.
For small retailers, service providers and local businesses, digital payments reduce the need to handle cash and can simplify transaction records.
Introducing merchant fees for selected payments could change the cost calculation for businesses that process large numbers of transactions.
A fee may appear small on an individual payment, but the cumulative effect can matter for businesses operating on narrow margins.
Larger merchants may also need to assess how the fee interacts with their payment providers and existing commercial arrangements.
Why the postponement matters
The decision to delay implementation gives payment companies and businesses more time to prepare for the proposed changes.
A transition involving a widely used payment network requires clear communication, technical readiness and an understanding of which transactions fall under the framework.
The additional time may also allow stakeholders to examine how the rules will be applied in practice.
However, the postponement does not by itself mean that the framework has been cancelled.
As of the October 13 report, the revised implementation date had not been notified. <Cite refs={[“turn794878search1”]}/>
What consumers should know
Consumers should not assume that the reported framework automatically introduces a charge on every UPI transfer.
The distinction between a consumer making a personal payment and a merchant accepting payment for goods or services is important.
Businesses should wait for the applicable official guidance and their payment providers’ instructions before changing their payment policies.
Consumers should also be cautious about viral messages claiming that all UPI payments will suddenly attract a percentage fee.
The larger question for digital payments
The debate highlights a long-running challenge for digital payment infrastructure: how to maintain an affordable payment system while ensuring that the companies and institutions supporting it can sustain their operations.
UPI has become a major part of India’s financial infrastructure, and changes to its pricing structure can have consequences across retail, commerce and financial technology.
The next key development will be the formal announcement of the revised timeline and final implementation details.