Key Highlights
- Lucknow-based crypto trader received an Income Tax notice of ₹88.55 lakh.
- Trader claimed he invested only ₹9.63 lakh in Bitcoin trading.
- He reported a loss of approximately ₹3.34 lakh.
- Tax authorities treated crypto purchases as unexplained investments.
- Income Tax Appellate Tribunal (ITAT) intervened and quashed the proceedings.
- Case highlights growing scrutiny of cryptocurrency transactions in India.
A Massive Tax Notice Over a Loss-Making Crypto Trade
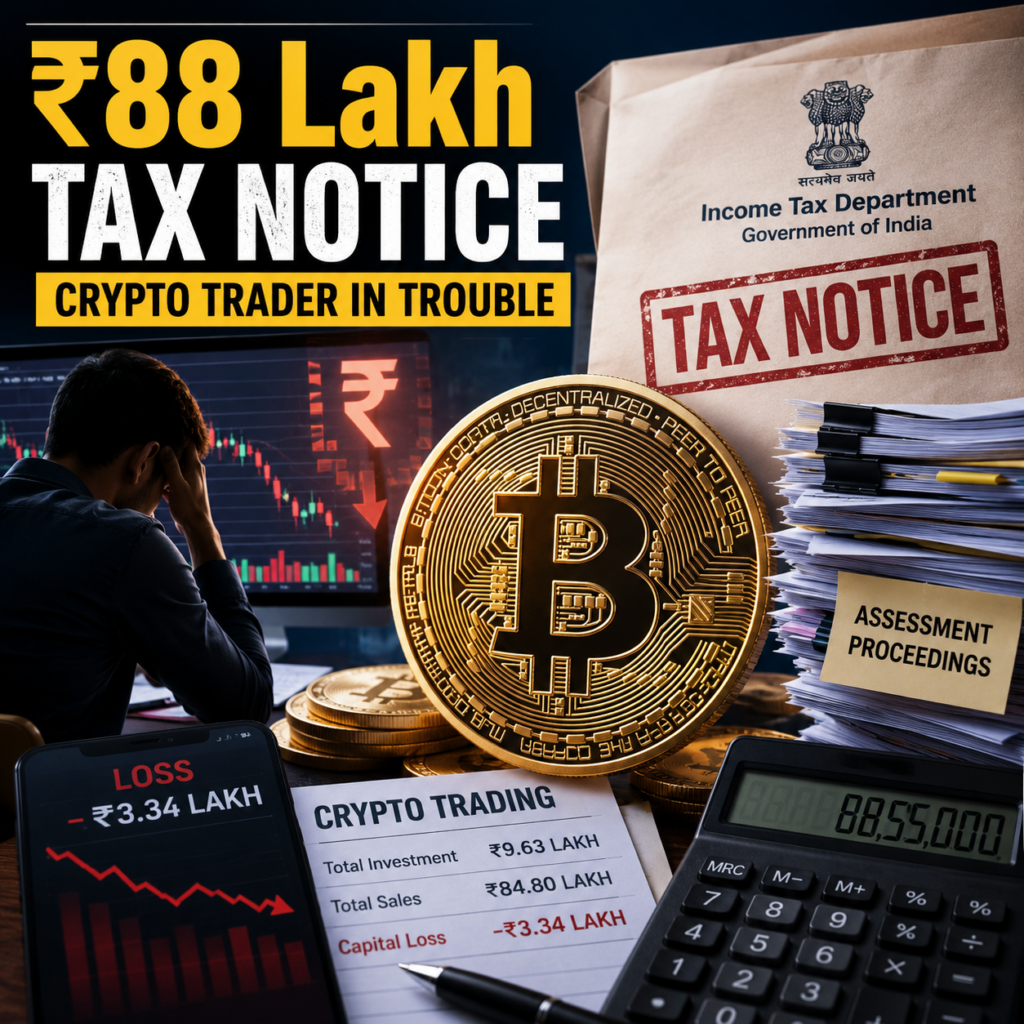
A cryptocurrency trader from Lucknow found himself at the center of a major tax dispute after receiving an Income Tax notice worth ₹88.55 lakh despite claiming that his actual investment in Bitcoin trading was only ₹9.63 lakh.
The trader maintained that he had not made any significant profits from cryptocurrency trading. Instead, he suffered a capital loss of around ₹3.34 lakh. However, tax authorities viewed the matter differently after examining his transaction records.
The case has now become one of the most talked-about cryptocurrency tax disputes in India.
How the Dispute Started
According to records presented before the Income Tax Appellate Tribunal (ITAT), the Income Tax Department obtained information through its Insight Portal indicating large Bitcoin transactions linked to the trader.
Reported Transaction Figures
- Total Bitcoin purchase transactions: Approximately ₹88.14 lakh
- Total sale proceeds: Approximately ₹84.80 lakh
- Reported capital loss: Around ₹3.34 lakh
- Tax notice amount: ₹88.55 lakh
The department questioned the source of funds used for these transactions and initiated reassessment proceedings.
Why the Tax Department Raised Questions
Tax officials argued that the trader could not adequately explain the source of funds behind cryptocurrency purchases worth ₹88.55 lakh.
As a result:
- The amount was treated as an “unexplained investment.”
- Proceedings were initiated under provisions of the Income Tax Act.
- Authorities considered the cumulative transaction value while assessing the case.
The department’s interpretation effectively treated the purchase volume as fresh investment.
Trader’s Defense
The taxpayer strongly disagreed with the department’s calculations.
His key arguments included:
- Actual capital deployed was only around ₹9.63 lakh.
- The same funds were repeatedly used for multiple buy-and-sell transactions.
- High transaction turnover did not mean he invested ₹88 lakh from external sources.
- Trading activity generated volume, but not equivalent new investment.
This is a common practice among active traders, where the same capital circulates through multiple trades over time.
What the ITAT Found
The Income Tax Appellate Tribunal did not directly decide whether the department’s investment calculation was correct.
Instead, the tribunal focused on procedural issues.
Important Findings
- A notice under Section 148A(b) was issued to the taxpayer.
- The taxpayer submitted a reply within the permitted period.
- Tax authorities passed their order before the response deadline had expired.
- The order incorrectly stated that no reply had been received.
According to the tribunal, the taxpayer was not given the full opportunity guaranteed under the law.
ITAT’s Decision
After reviewing the facts, the ITAT concluded that proper legal procedure had not been followed.
Tribunal Ruling
✓ Reassessment proceedings were quashed.
✓ Relief was granted to the taxpayer.
✓ The importance of due process was reaffirmed.
The ruling was based primarily on procedural lapses rather than a final determination of the taxability of the crypto transactions.
Why This Case Matters
This case serves as an important warning for cryptocurrency investors across India.
Key Takeaways
- Large crypto transaction volumes can attract tax scrutiny.
- Loss-making traders are not immune from investigation.
- Maintaining detailed transaction records is essential.
- Sources of funds should be properly documented.
- Exchange statements and trade histories should be preserved.
- Procedural fairness remains crucial in tax proceedings.
The Bigger Picture
As India continues refining its cryptocurrency taxation framework, cases like this demonstrate the challenges authorities face when interpreting digital asset transactions.
For investors, the message is clear:
Keep accurate records, report transactions correctly, and maintain complete documentation of all crypto-related activities.
The Lucknow trader’s experience shows that even when a trader reports losses, misunderstandings regarding transaction volume and investment amounts can lead to substantial tax disputes.